Last month saw 368 VC investments across Europe, with $9.8 billion invested in total – a 573% increase in funding volume compared to September last year.
Number and volume of announced funding rounds over the past 12 months*
- Number of funding rounds
- Invested volume in $bn
Leading Industries and Investors
According to the number of conducted investments, AI leads with 182 investments, followed by Health Care with 152 and FinTech with 84, each ahead of the next industry, BioTech (39).
BII Venture Lab was the most active investors with 15 investments. Followed by Y Combinator (9), Bpifrance (7), Mercia Ventures and HTGF with 6 investments each rounding out the top five most active investors.
Top 10 Industries of Financed Startups
- AI
- Health Care
- FinTech
- BioTech
- Manufacturing
- Energy
- Marketing
- Food and Beverage
- Web
- Retail
Top 5 Investors with the highest number of deals
- BBI Venture Lab
- Y Combinator
- Bpifrance
- Mercia Ventures
- HTGF
Notable funding rounds across Europe
In September, the largest funding round was a $3.49 billion Series D by Mistral AI, a Prais-based Venture which develops artificial intelligence models, applications, and infrastructure for organizations and developers. Founded in 2023 in France, Mistral AI raised the investment mainly to massively expand frontier research and training compute and to scale its full-stack sovereign AI offering.
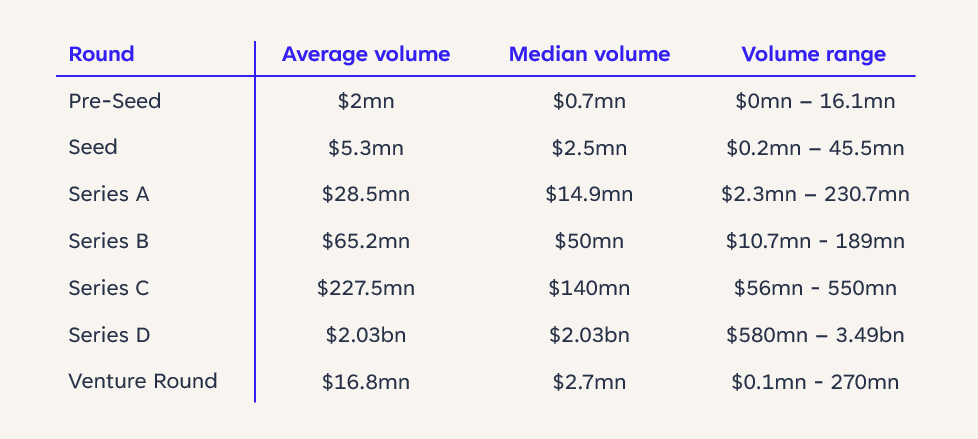
Seed Rounds made up the largest share of rounds (39%). Despite that, the largest volume of $4.07bn was invested in 2 Series D Rounds.
The largest Seed Round was secured by Aptadir Therapeutics, a Milan-based company developing a treatment for Myelodysplastic Neoplasms based on the capability of specific RNA therapeutics. Founded in 2024 in Italy, Aptadir Therapeutics raised $45.5 million (€40 million) in September.
Number and total volume of financing rounds per stage
- Number of funding rounds per stage
- Volume of financing rounds per stage in $mn
Detailed overview by stage
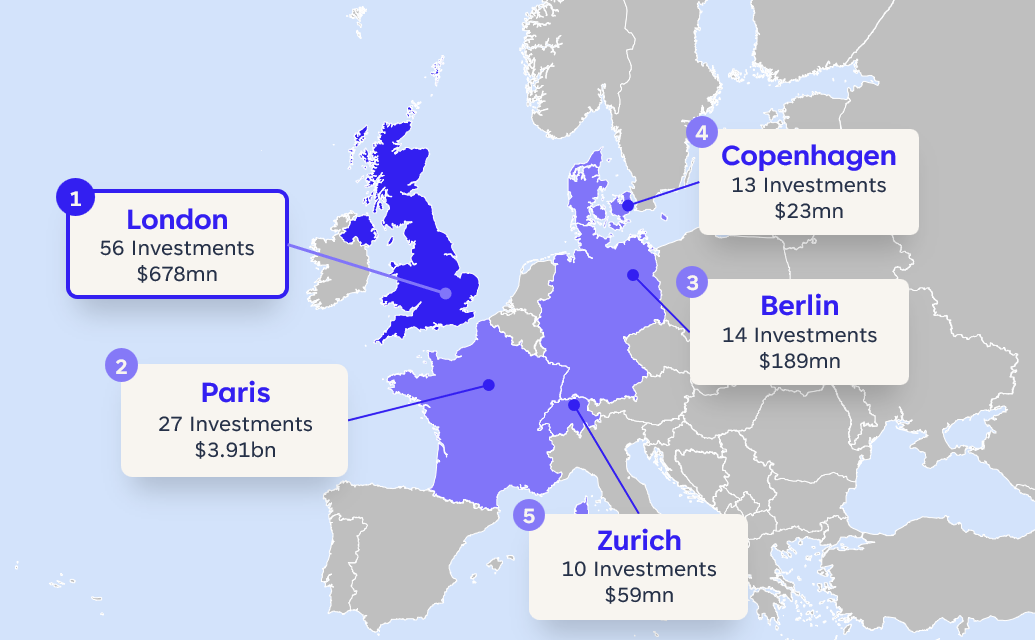
European VC Industry Hotspots
In September, London remained the leading hotspot for European VC by number of investments (56), followed by Paris (27), Berlin (14), Copenhagen (13) and Zurich (10).
The most investments were conducted in the UK (99), followed by France (46) and Germany (43).
When ranked by investment volume rather than the number of investments, Paris takes the top 1 spot ($3.91bn) with 27 investments and Amsterdam ($614mn) with nine investments, Lisbon ($580mn) with one investment and Munich ($474mn) with seven investments join London and Paris in the top 5 cities.
VC Exit Overview
This month, 37 exits without an IPO took place.
With 10 exits, AI companies represent the largest exit industry of the month, followed by EdTech (8) and Web (5) companies.
Most exited companies are based in France with 10 exits, followed by the UK with 6 exits.
- Number of Acquisition Exits
- Number of IPO Exits
PE Acquisitions Overview
In September, 46 PE acquisitions (11% of all VC and PE investment rounds) were conducted, a decrease of 2pp compared to last month.
With 14 acquisitions, the UK saw the highest number of companies acquired in September.
Manufacturing (8), Health Care (8) and FinTech (7) were the top acquisition industries mentioned.
The standout deal was Veritas Capital’s £~1.9 billion acquisition of Bodycote, a company which provides thermal processing and metallurgical services that modify the properties of metals and alloys.
- % of all investment rounds
- Number of PE acquisitions
*All data from CrunchBase, as of October 1, 2026.
Partner with us
Unlock the full potential of your financial strategy with Trustventure’s expert guidance. Whether you’re navigating challenges in the financial sector, seeking advice on corporate financing, or enhancing your planning and controlling processes, we’re here to empower your journey and help you create transparency and confidence for you and your investors.
Ready to elevate your financial game? Reach out to us today using our contact form or drop us a direct message at office@trustventure.de. Work with us to achieve your financial success! 🚀
Other articles
 M&A European Roll-Up Market Report – August 2026
August 2026 presented a 20% year-over-year decrease in the number of PE-backed acquisitions. In addition to FinTech, private equity investors are also targeting Software and Marketing. Learn all about it in our report and case study, including ETL Systems' acquisition of Amphinicy Technologies.
September 11, 2026
 VC Landscape European Venture Capital Landscape – August 2026
With 200 investments and $2.8 billion raised across Europe, August saw a 53% decrease in volume and 38% fall in deal count month over month. The largest round of the month was a $400 million Series C by the Stockholm-based company Lovable a company which provides an AI-driven platform enabling users to generate and deploy web applications and websites from natural language prompts.
September 7, 2026
 M&A European Roll-Up Market Report – July 2026
July 2026 presented a 20% year-over-year decrease in the number of PE-backed acquisitions. In addition to FinTech, private equity investors are also targeting Health Care and Consulting. Learn all about it in our report and case study, including Kafeterija’s acquisition of Eddy's.
August 19, 2026
 VC Landscape European Venture Capital Landscape – July 2026
With 321 investments and $6.0 billion raised across Europe, July saw a 19% decrease in volume and 24% fall in deal count month over month. The largest round of the month was a $1.2 billion Series D by the Gilching-based company Quantum Systems a company which builds AI-powered eVTOL drones for defense, security, and surveying, specializing in aerial intelligence solutions.
August 11, 2026
 VC Landscape Germany Venture Capital Landscape – Q2 2026
Between an increase of 5% in invested VC volume and a €600mn funding round in the DefenseTech space, Germany is closing its venture capital landscape Q2 2026. Learn all about it in our latest analysis.
July 22, 2026
 VC Landscape European Venture Capital Landscape – June 2026
With 420 investments and $7.5 billion raised across Europe, June saw a 18% increase in volume and 43% rise in deal count month over month. The largest round of the month was a $1.4 billion Series C by the Metzingen-based company Neura a company which builds AI-powered cognitive robots for industrial and everyday use.
July 21, 2026
 M&A European Roll-Up Market Report – June 2026
June 2026 presented a 3% year-over-year decrease in the number of PE-backed acquisitions. In addition to Software, private equity investors are also targeting FinTech, Health Care and Consulting. Learn all about it in our report and case study, including Blend360’s acquisition of In516ht.
July 8, 2026
 M&A European Roll-Up Market Report – May 2026
May 2026 presented a 45% year-over-year increase in the number of PE-backed acquisitions. In addition to Marketing, private equity investors are also targeting Software, FinTech and Consulting. Learn all about it in our report and case study, including RSK’s acquisition of HV Energy Systems.
June 15, 2026
 VC Landscape European Venture Capital Landscape – May 2026
With 293 investments and $6.3 billion raised across Europe, May saw a 31% increase in volume and 10% decrease in deal count month over month. The largest round of the month was a $2.1 billion Series B by the London-based company Isomorphic Labs an AI-first drug design and develoment company that transforms drug discovery to design and evaluate new medicines.
June 8, 2026