Last month saw 321 VC investments across Europe, with $4.1 billion invested in total – a 45% decrease in funding volume compared to October last year.
Number and volume of announced funding rounds over the past 12 months*
- Number of funding rounds
- Invested volume in $bn
Leading Industries and Investors
According to the number of conducted investments, AI leads with 144 investments, followed by Health Care with 90 and FinTech with 57, each ahead of the next industry, BioTech (31).
SFC Capital, Antler, Creandum and Bpifrance were the most active investors with 6 investments each. Followed by British Business Bank with 4 investments rounding out the top five most active investors.
Top 10 Industries of Financed Startups
- AI
- Health Care
- FinTech
- BioTech
- Web
- Manufacturing
- Energy
- Marketing
- PropTech
- Retail
Top 5 Investors with the highest number of deals
- SFC Capital
- Antler
- Bpifrance
- Creandum
- British Business Bank
Notable funding rounds across Europe
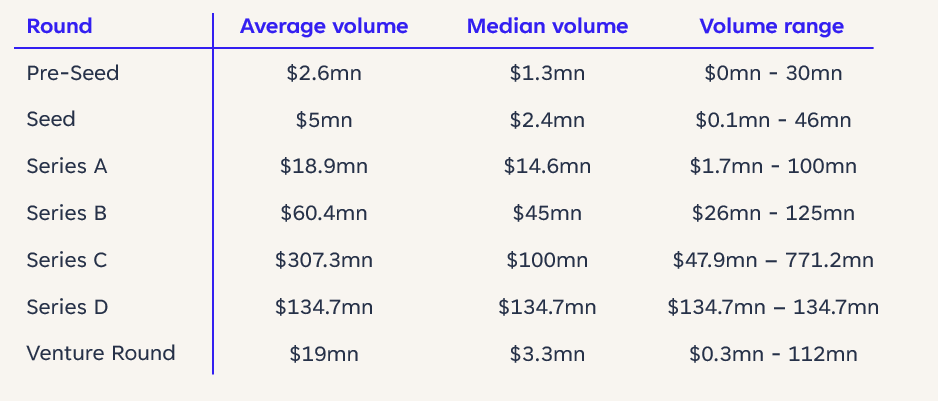
In October, the largest funding round was a $771 million Series C by Fractile, a London-based Venture which develops specialized semiconductor hardware and computing systems for advanced AI models. Founded in 2022 in the UK, Fractile raised the investment mainly to bring its first inference chips into volume production ahead of data-centre deployment in 2027 and to scale its hardware and software teams across London, Bristol, San Francisco and Taipei.
Seed Rounds made up the largest share of rounds (42%). Despite that, the largest volume of $1.23bn was invested in 5 Series C Rounds.
The largest Seed Round was secured by Flow Games, an Istanbul-based fast-rising mobile game developer that became one of the breakout stars of the hybrid casual puzzle market. Founded in 2025 in Turkey, Flow Games raised $46 million (€41 million) in October.
Number and total volume of financing rounds per stage
- Number of funding rounds per stage
- Volume of financing rounds per stage in $mn
Detailed overview by stage
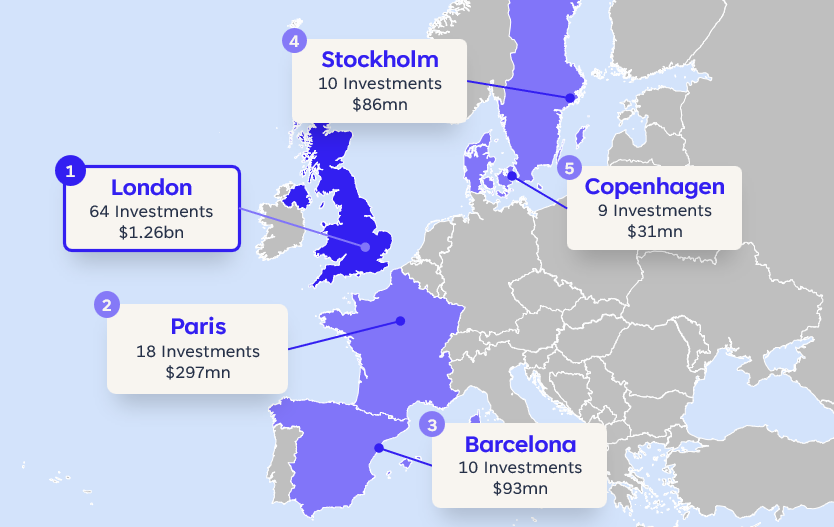
European VC Industry Hotspots
In October, London remained the leading hotspot for European VC by number of investments (64), followed by Paris (18), Barcelona (10), Stockholm (10) and Copenhagen (9).
The most investments were conducted in the UK (108), followed by France (31) and Spain (29).
When ranked by investment volume rather than the number of investments, Oxford ($470mn) with four investments, Basel ($145mn) with two investments and Valencia ($121mn) with three investments join London and Paris in the top 5 cities.
VC Exit Overview
This month, 40 exits without an IPO took place.
With 16 exits, FinTech companies represent the largest exit industry of the month, followed by Health Care (9) and AI (7) companies.
Most exited companies are based in the UK with 9 exits, followed by Germany with 7 exits.
- Number of Acquisition Exits
- Number of IPO Exits
PE Acquisitions Overview
In October, 50 PE acquisitions (13% of all VC and PE investment rounds) were conducted, an increase of 2pp compared to last month.
With 12 acquisitions, the UK saw the highest number of companies acquired in October.
Food & Beverage (16), Manufacturing (12) and Health Care (10) were the top acquisition industries mentioned.
The standout deal was EQT’s €~10.8 billion acquisition of Qiagen, a company which provides technologies and products for preanalytical sample preparation and linked molecular assay solutions.
- % of all investment rounds
- Number of PE acquisitions
*All data from CrunchBase, as of November 2, 2026.
Partner with us
Unlock the full potential of your financial strategy with Trustventure’s expert guidance. Whether you’re navigating challenges in the financial sector, seeking advice on corporate financing, or enhancing your planning and controlling processes, we’re here to empower your journey and help you create transparency and confidence for you and your investors.
Ready to elevate your financial game? Reach out to us today using our contact form or drop us a direct message at office@trustventure.de. Work with us to achieve your financial success! 🚀
Other articles
 M&A European Roll-Up Market Report – September 2026
September 2026 presented a 12% year-over-year decrease in the number of PE-backed acquisitions. In addition to Software, private equity investors are also targeting FinTech and Consulting. Learn all about it in our report and case study, including HR Path's acquisition of tts digital HR experts.
October 21, 2026
 VC Landscape Germany Venture Capital Landscape – Q3 2026
Between an increase of 2% in invested VC volume and a €1.04bn funding round in the DefenseTech space, Germany is closing its venture capital landscape Q3 2026. Learn all about it in our latest analysis.
October 14, 2026
 VC Landscape European Venture Capital Landscape – September 2026
With 368 investments and $9.8 billion raised across Europe, September saw a 250% increase in volume and 84% risse in deal count month over month. The largest round of the month was a $3.49 billion Series D by the Paris-based company Mistral AI a company which develops artificial intelligence models, applications, and infrastructure for organizations and developers.
October 7, 2026
 M&A European Roll-Up Market Report – August 2026
August 2026 presented a 20% year-over-year decrease in the number of PE-backed acquisitions. In addition to FinTech, private equity investors are also targeting Software and Marketing. Learn all about it in our report and case study, including ETL Systems' acquisition of Amphinicy Technologies.
September 11, 2026
 VC Landscape European Venture Capital Landscape – August 2026
With 200 investments and $2.8 billion raised across Europe, August saw a 53% decrease in volume and 38% fall in deal count month over month. The largest round of the month was a $400 million Series C by the Stockholm-based company Lovable a company which provides an AI-driven platform enabling users to generate and deploy web applications and websites from natural language prompts.
September 7, 2026
 M&A European Roll-Up Market Report – July 2026
July 2026 presented a 20% year-over-year decrease in the number of PE-backed acquisitions. In addition to FinTech, private equity investors are also targeting Health Care and Consulting. Learn all about it in our report and case study, including Kafeterija’s acquisition of Eddy's.
August 19, 2026
 VC Landscape European Venture Capital Landscape – July 2026
With 321 investments and $6.0 billion raised across Europe, July saw a 19% decrease in volume and 24% fall in deal count month over month. The largest round of the month was a $1.2 billion Series D by the Gilching-based company Quantum Systems a company which builds AI-powered eVTOL drones for defense, security, and surveying, specializing in aerial intelligence solutions.
August 11, 2026
 VC Landscape Germany Venture Capital Landscape – Q2 2026
Between an increase of 5% in invested VC volume and a €600mn funding round in the DefenseTech space, Germany is closing its venture capital landscape Q2 2026. Learn all about it in our latest analysis.
July 22, 2026
 VC Landscape European Venture Capital Landscape – June 2026
With 420 investments and $7.5 billion raised across Europe, June saw a 18% increase in volume and 43% rise in deal count month over month. The largest round of the month was a $1.4 billion Series C by the Metzingen-based company Neura a company which builds AI-powered cognitive robots for industrial and everyday use.
July 21, 2026