OKAPI:Orbits is a SaaS startup dedicated to making space travel more sustainable through Collision Avoidance Software for satellites.
Invested VC volume increased by 59% in Germany compared to Q2 2024
Number and volume of announced funding rounds over the last year*
- Number of funding rounds
- Invested volume in $bn
* All data from CrunchBase, as of July 4, 2025
AI startups saw the most investments in Q2
In Q2, AI startups lead with 39 investments, followed by Health Care (36) and FinTech startups (28).
Top 10 industries of financed startups according to the number of conducted investments
- AI
- Health Care
- FinTech
- Energy
- CleanTech
- Manufacturing
- Web
- Biotech
- Telecommunications
- Food and Beverage
Number and total volume of financing rounds per stage
- Number of funding rounds
- Invested volume in $bn
The largest funding round in the clean energy space of Q2
Berlin-based Proxima Fusion secured a €250 million Series A Round, the largest funding round in Germany of the quarter in the clean energy space.
Most investment rounds were Seed Rounds (41%). Despite that, the largest volume of $694 million was invested in just 1 Series D Round.

HTGF was the most active VC investor in Germany
Regarding the investors behind those funding rounds, the HTFG emerged as the most active VC investor, completing 7 deals. With this, it leads ahead of Angel Invest, Capnamic (5 deals), Bayern Kapital (4 deals) and D11Z.Ventures (3 Deals) among the top 5.
Investors with the highest number of investments in Q2 2025 Germany VC + PE Landscape – Q1 2025
- HTGF
- Angel Invest
- Capnamic
- Bayern Kapital
- D11Z.Ventures
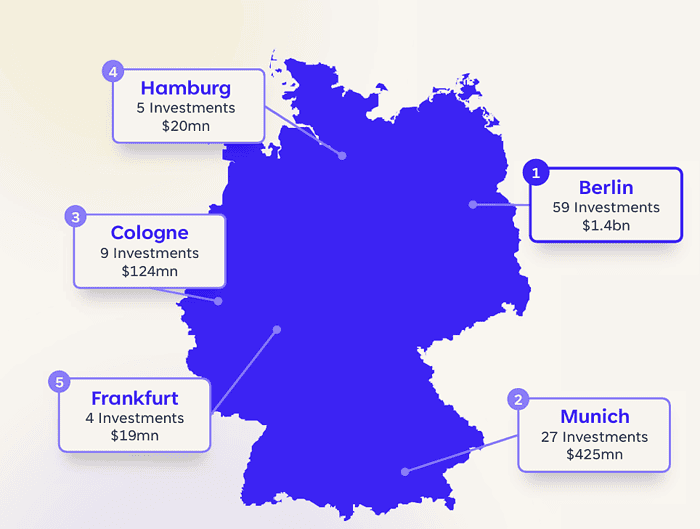
Berlin remains Germany’s VC hotspot, while Munich takes the 2nd spot
The most investments in Q2 were conducted in Berlin (59), followed by Munich (27) and Cologne (9).
When ranking by investment volume instead of the number of conducted investments, Gilching ($181 mn) and Aachen ($43 mn) replaces Hamburg and Frankfurt in the Top 5.
In the spotlight
The largest Seed-Round in Q2 was raised in Lower Saxony
Lower Saxony at a glance (see also Invest in Niedersachsen)
~1000 verified startups
67% of startup are founded outside of major cities
More female founders (20%) than the national average
Reneo raised €45 million

Industry
Satellite Communication
Founded in
2018, Brunswick
Money raised
€15 million
Type of financing round
Seed
About
Lead Investor

Private Equity acquisitions increased by 35% compared to the previous year
- Number of PE acquisitions
- Share of all investment rounds (in %)
Number and share of PE acquisitions increased in Germany
In Q2 2025, 11 PE acquisitions were conducted in Germany, representing a share of 7% of all investment rounds (VC + PE) (157).
Most companies were acquired in Baden Württemberg, Lower Saxony, NRW and Bayernwith 2 acquisitions each.
IK Partners was the most active acquirer, completing 2 acquisitions in Q2.
PE acquisition highlight in Q2


Partner with us
Unlock the full potential of your financial strategy with Trustventure‘s expert guidance. Whether you’re navigating challenges in the financial sector, seeking advice on corporate financing, or enhancing your planning and controlling processes, we’re here to empower your journey and help you create transparency and confidence for you and your investors.
Ready to elevate your financial game? Reach out to us today using our contact form or drop us a direct message at office@trustventure.de. Work with us to achieve your financial success! 🚀
Other articles
 M&A European Roll-Up Market Report – August 2026
August 2026 presented a 20% year-over-year decrease in the number of PE-backed acquisitions. In addition to FinTech, private equity investors are also targeting Software and Marketing. Learn all about it in our report and case study, including ETL Systems' acquisition of Amphinicy Technologies.
September 11, 2026
 VC Landscape European Venture Capital Landscape – August 2026
With 200 investments and $2.8 billion raised across Europe, August saw a 53% decrease in volume and 38% fall in deal count month over month. The largest round of the month was a $400 million Series C by the Stockholm-based company Lovable a company which provides an AI-driven platform enabling users to generate and deploy web applications and websites from natural language prompts.
September 7, 2026
 M&A European Roll-Up Market Report – July 2026
July 2026 presented a 20% year-over-year decrease in the number of PE-backed acquisitions. In addition to FinTech, private equity investors are also targeting Health Care and Consulting. Learn all about it in our report and case study, including Kafeterija’s acquisition of Eddy's.
August 19, 2026
 VC Landscape European Venture Capital Landscape – July 2026
With 321 investments and $6.0 billion raised across Europe, July saw a 19% decrease in volume and 24% fall in deal count month over month. The largest round of the month was a $1.2 billion Series D by the Gilching-based company Quantum Systems a company which builds AI-powered eVTOL drones for defense, security, and surveying, specializing in aerial intelligence solutions.
August 11, 2026
 VC Landscape Germany Venture Capital Landscape – Q2 2026
Between an increase of 5% in invested VC volume and a €600mn funding round in the DefenseTech space, Germany is closing its venture capital landscape Q2 2026. Learn all about it in our latest analysis.
July 22, 2026
 VC Landscape European Venture Capital Landscape – June 2026
With 420 investments and $7.5 billion raised across Europe, June saw a 18% increase in volume and 43% rise in deal count month over month. The largest round of the month was a $1.4 billion Series C by the Metzingen-based company Neura a company which builds AI-powered cognitive robots for industrial and everyday use.
July 21, 2026
 M&A European Roll-Up Market Report – June 2026
June 2026 presented a 3% year-over-year decrease in the number of PE-backed acquisitions. In addition to Software, private equity investors are also targeting FinTech, Health Care and Consulting. Learn all about it in our report and case study, including Blend360’s acquisition of In516ht.
July 8, 2026
 M&A European Roll-Up Market Report – May 2026
May 2026 presented a 45% year-over-year increase in the number of PE-backed acquisitions. In addition to Marketing, private equity investors are also targeting Software, FinTech and Consulting. Learn all about it in our report and case study, including RSK’s acquisition of HV Energy Systems.
June 15, 2026
 VC Landscape European Venture Capital Landscape – May 2026
With 293 investments and $6.3 billion raised across Europe, May saw a 31% increase in volume and 10% decrease in deal count month over month. The largest round of the month was a $2.1 billion Series B by the London-based company Isomorphic Labs an AI-first drug design and develoment company that transforms drug discovery to design and evaluate new medicines.
June 8, 2026
 VC Landscape Germany Venture Capital Landscape – Q1 2026
Between an increase of 6.5% in invested VC volume and a €350mn funding round in the AI space, Germany is closing its venture capital landscape Q1 2026. Learn all about it in our latest analysis.
May 20, 2026